Course contents
Where market income lands
Indian tax law sorts all income into a few heads, and the money from markets can land under capital gains, business income, or other sources depending on what you did. Knowing the map is the first step to knowing your own position.
- Introduce the heads of income at a beginner level
- Place trading and investing income under capital gains, business income, and other sources
- Preview that the classification decides the rules
The Income Tax Department does not look at your year and see a single lump called "money you made." It sorts every rupee of income into one of a few labelled boxes, called heads of income, and the box your market income falls into decides how it is taxed: the rate, what you can deduct, and which form you file. So before any rule about rates or deductions makes sense, you need the map, the heads of income, and where a trader and an investor fit on it.
The five heads of income
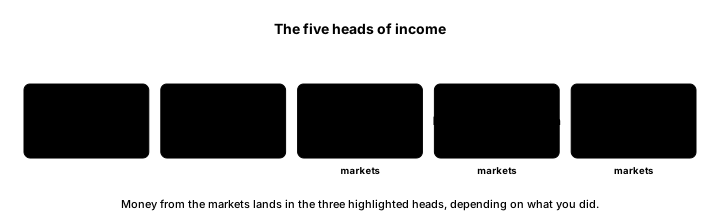
Indian tax law groups all income under five heads. Most people meet only two or three of them, but it helps to see the whole map.
The first is Salaries, the income an employee earns from a job. The second is Income from House Property, chiefly the rent from property you own. The third is Profits and Gains of Business or Profession, often shortened to PGBP, the income from running a business or practising a profession. The fourth is Capital Gains, the profit from selling a capital asset such as shares, mutual funds, property, or gold. The fifth is Income from Other Sources, a catch-all for income that does not fit the others, such as interest and dividends.
Your total income for the year is the sum across whichever heads apply to you, and the rules differ from head to head, which is exactly why the classification matters.
Where a trader's and investor's money lands
For someone active in the markets, three of these five heads do the work.
Money made from selling investments you held as capital assets, a few shares bought and held for months or years, an equity mutual fund, some gold, lands under Capital Gains. This is the investor's head, and Part 2 of this course is devoted to it.
Money made from trading as a business, most clearly from futures and options, and from frequent buying and selling done as an activity rather than as investment, lands under Profits and Gains of Business or Profession. This is the trader's head, and it carries its own internal split, which a later chapter draws, between speculative income (such as intraday equity trading) and non-speculative income (such as F&O). Part 3 covers it in full.
And the income you earn simply for holding investments, the dividends on your shares and the interest on your deposits and bonds, lands under Income from Other Sources. It is taxed as it arrives, whether or not you ever sell.
So a single person can easily touch three heads at once: a salary from a job, capital gains from a long-held mutual fund, business income from F&O trading, and dividends under other sources, each taxed by its own rules and all added together into one total income.
Why the box matters so much
The reason to start here is that almost every question in the rest of the course, what rate applies, whether you can deduct your costs, whether you must keep books or get an audit, which return you file, depends first on which head your income belongs to. The same activity, buying and selling shares, can fall under capital gains for one person and under business income for another, and the tax outcome differs sharply between the two. Getting the head right is therefore the foundation on which a correct return is built, and getting it wrong can misstate everything above it.
That single most important fork, between capital gains and business income, is important enough that the next chapter is devoted entirely to it.
What to carry forward
Tax law sorts all income into five heads, and a market participant's income lands mainly under three: capital gains for selling investments, business income for trading as a business including F&O, and other sources for the dividends and interest you earn just by holding. The head decides the rate, the deductions, and the form, which is why identifying it correctly comes before every other tax question.
The most consequential of those choices is the fork between capital gains and business income, because the same buying and selling of shares can fall on either side with very different results. The next chapter is about that fork: whether you are, in the eyes of tax law, an investor or a trader.